


East Asia remains a global video game powerhouse, albeit with ongoing economic headwinds. Japan and South Korea, the world’s third- and fourth-largest video game markets, make up the region which continues to shape global video game culture and global industry trends by being home to iconic IPs, major game publishers, and companies whose influence spans the globe. Consequently, Japan and Korea also represent some of the largest, most mature gaming markets across Asia & MENA.

From Japan and Korea to the world, major publishers have been exporting hit titles to global markets for years (Photo credit: Darang Candra, Tokyo Game Show 2026)
The region generated $28.2 billion in revenue in 2025, representing a 3.17% year-over-year decline, primarily driven by weaker player spending in Japan and broader macroeconomic challenges, including currency fluctuations. Looking ahead, the outlook is more optimistic. Revenue is forecast to rise 1.2% to $28.6 billion in 2026 and reach $32.0 billion by 2030, reflecting a five-year CAGR of 2.5%.
East Asia: Untapping Lucrative Monetization Potentials
What continues to set East Asia apart is its remarkable player monetization. The region boasts the highest average revenue per user (ARPU) globally, with annual ARPU expected to exceed $300 by 2028.
South Korea leads the way, with ARPU touching $371 in 2025, more than $100 higher than neighboring Japan. While Japan navigates its own unique macro challenges, upcoming growth drivers including the strong performance of the Nintendo Switch 2 and increased PC gaming spend are expected to support a market recovery. Meanwhile, South Korea’s improving economic outlook, growing console segment, and rising mobile game ARPU point to a positive growth trajectory.
Key Player Trends Shaping Japan and Korea
Beyond revenue, player behavior reveals some fascinating shifts, with a notable one being the rapid growth of older gamers and rising engagement with video content:
- Players aged over 46 now represent 31.6% of gamers in Japan and 26.6% in Korea, with this age group both seeing notable year-over-year increases.
- Video content also remains deeply embedded in gaming culture: 46.1% of Japanese gamers and 50.7% of Korean gamers regularly watching game livestreams or videos.
- 2% of surveyed Japanese players prefer single-player games: The highest share across all Asia & MENA markets tracked by Niko Partners.
- Korea’s mobile gaming ecosystem is diversifying, with third-party app stores’ share rising from 17% to 20.9%.
Fill out this form below to download select key takeaways from the report
These insights come from surveys conducted by Niko Partners, covering 1,130 gamers in Japan and 1,073 gamers in South Korea. The study defines gaming revenue as total player spending across premium game purchases, subscriptions, and in-app purchases, including transactions made through app stores, third-party platforms, and web shops. Gamers are defined as individuals who have played on PC, console, or mobile at least once during the previous week.
East Asia’s gaming market may be facing short-term economic headwinds, but strong player engagement, increasing monetization, and evolving consumer behavior suggest a resilient market poised for long-term growth.
At Niko Partners, we help businesses turn market intelligence into action. Through our syndicated research, subscription-based insights, and custom consulting services, we provide the data, analysis, and strategic guidance needed to navigate the rapidly evolving gaming markets across Asia and MENA. Whether you are evaluating market expansion opportunities, analyzing player behavior, assessing monetization strategies, or tracking regulatory developments, our research helps organizations make informed business decisions with confidence. Contact us to learn how Niko Partners can help your organization identify growth opportunities and build successful strategies in one of the world’s largest and most dynamic gaming markets.

China’s video game market reached a new milestone in 2025, generating $51.8 billion in revenue, up 5.4% year-over-year and surpassing Learn more >
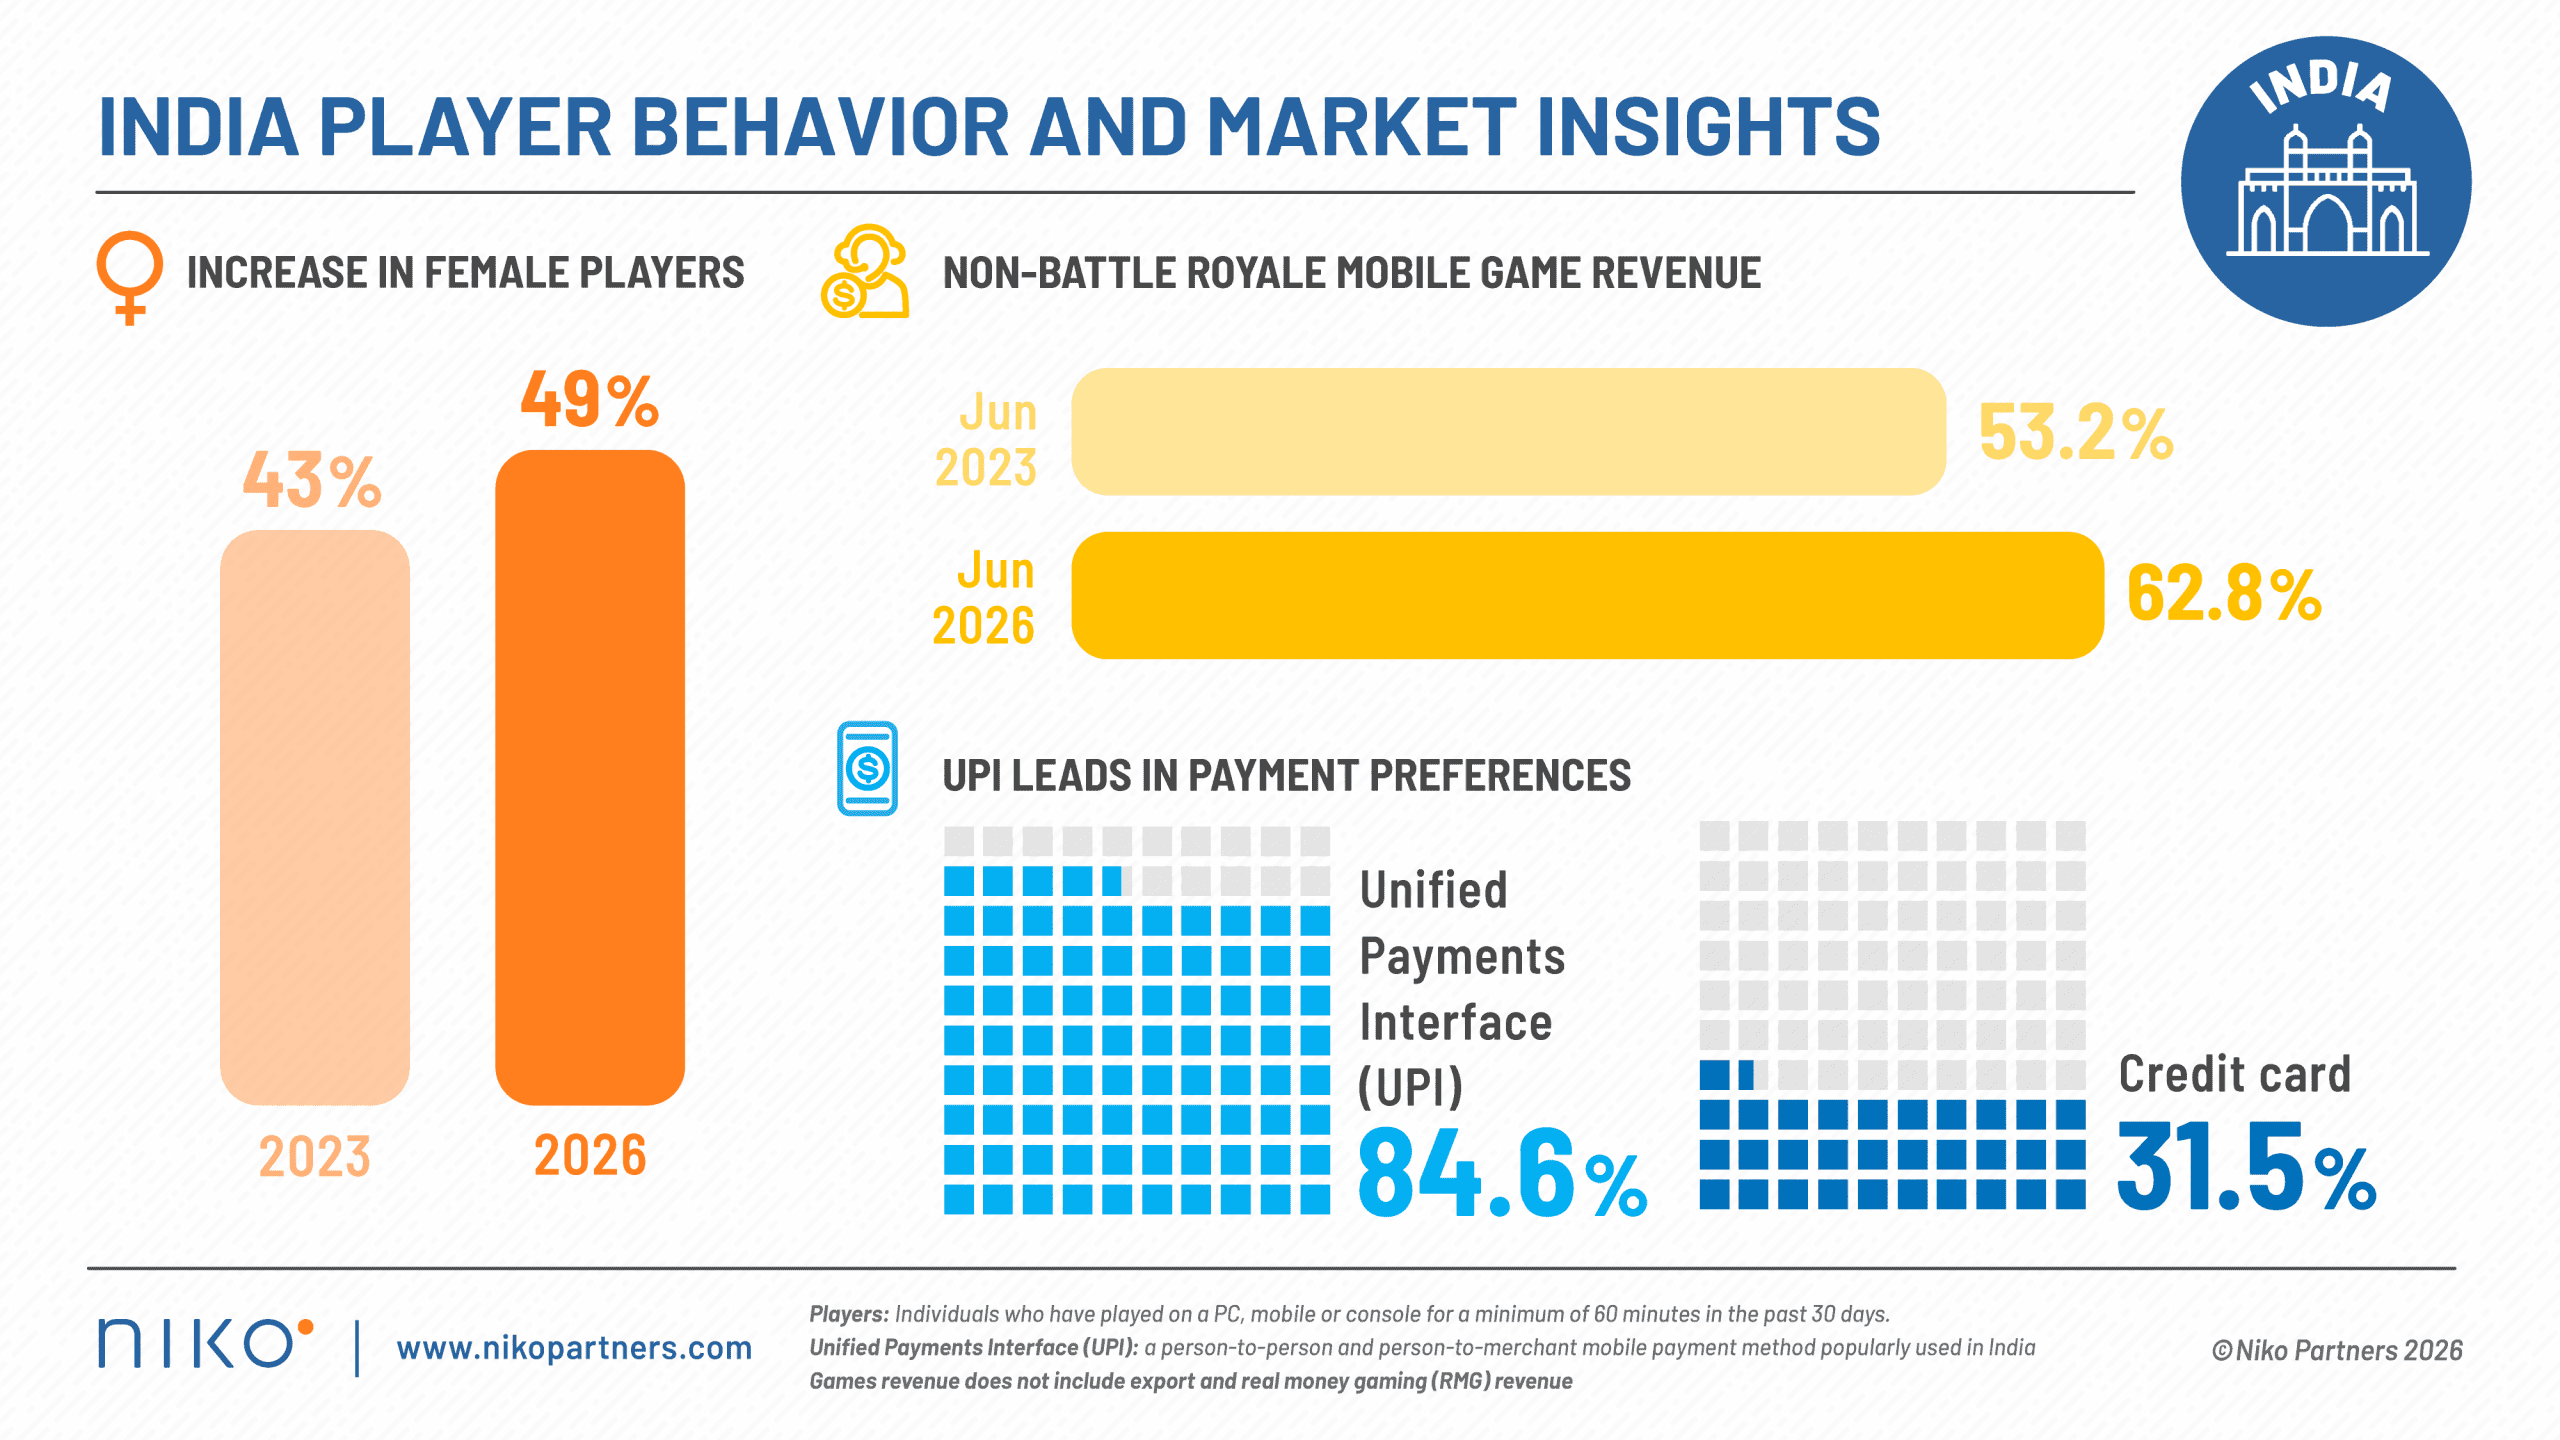
(updated on August 26 with a clarification on Generative AI sentiment) India's gaming market reached a major milestone in 2025, Learn more >
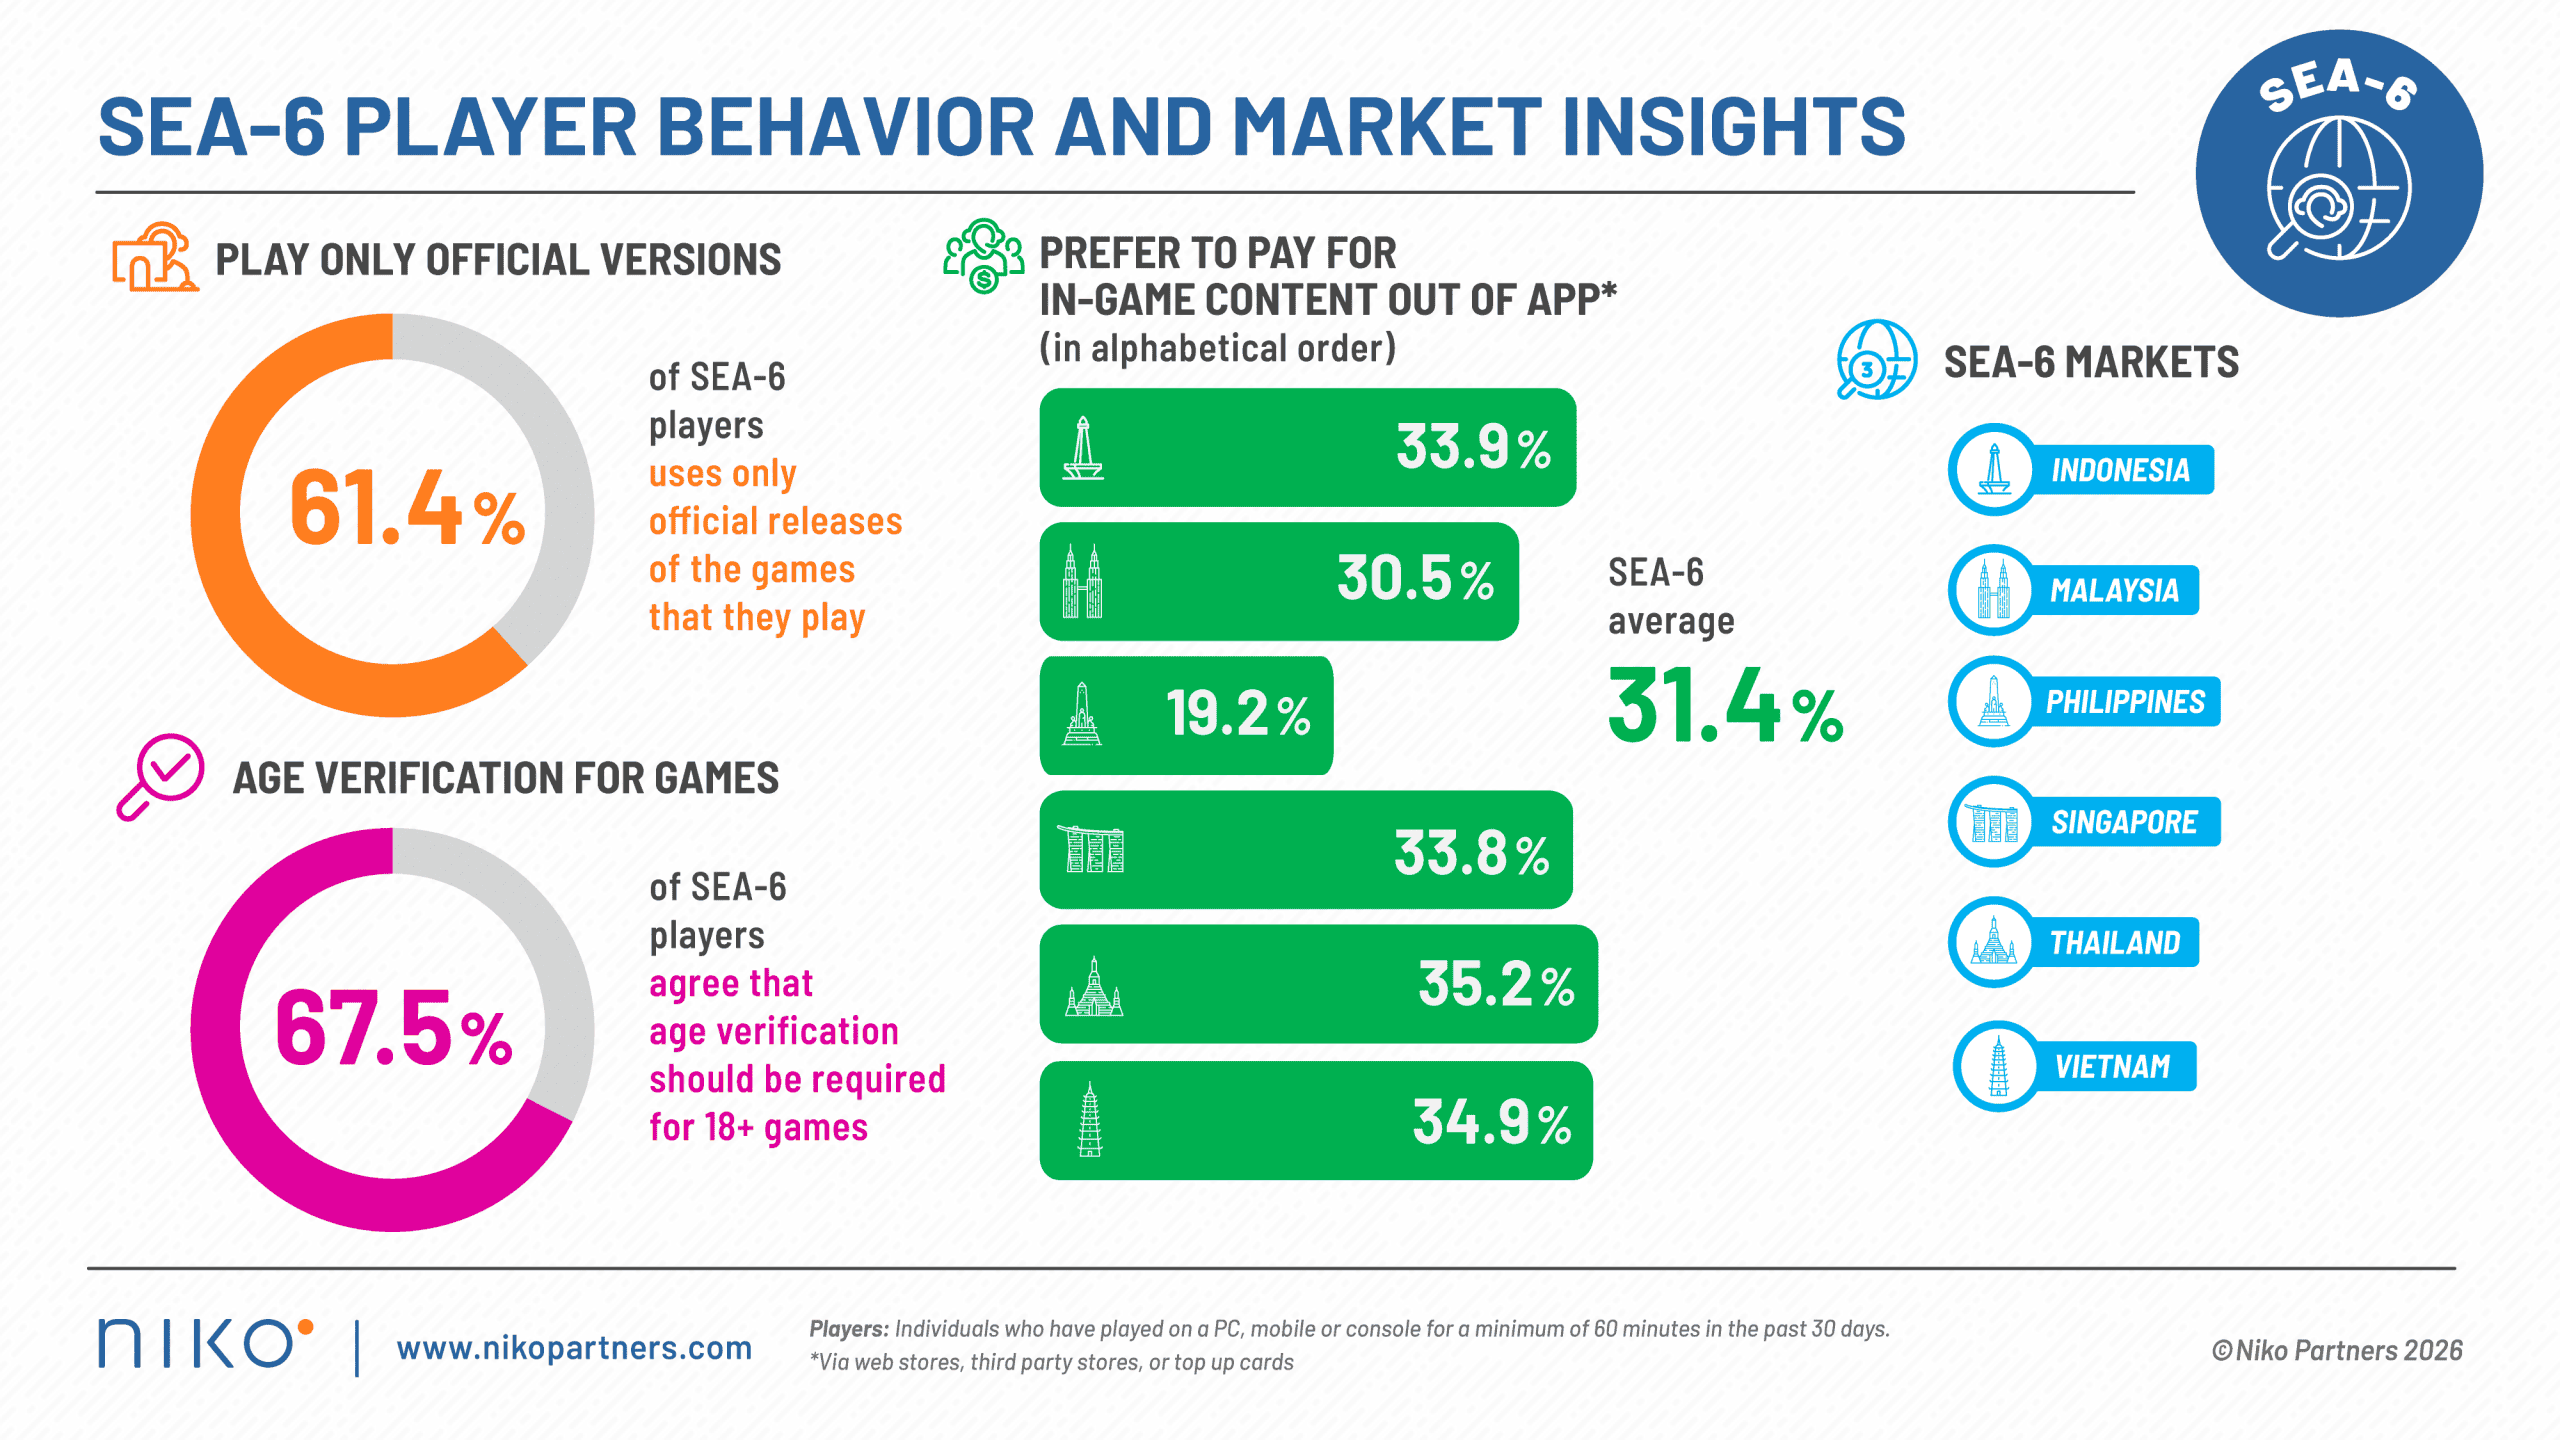
Video game markets in Southeast Asia are entering a new chapter of growth, driven by an expanding player base, increasing Learn more >
China’s video game market reached a new milestone in 2025, generating $51.8 billion in revenue, up 5.4% year-over-year and surpassing Learn more >
(updated on August 26 with a clarification on Generative AI sentiment) India's gaming market reached a major milestone in 2025, Learn more >
Video game markets in Southeast Asia are entering a new chapter of growth, driven by an expanding player base, increasing Learn more >